HELOC vs. HELOAN: The Core Difference Is Revolving Credit Versus a Lump Sum
Both products can use home equity without replacing the first mortgage, but one is revolving credit and the other is usually a…
Read feature → Request Options
An entire issue devoted to the differences between a HELOC and a home equity loan: revolving versus lump-sum funding, variable versus fixed rates, payment mechanics, fees, and decision scenarios.
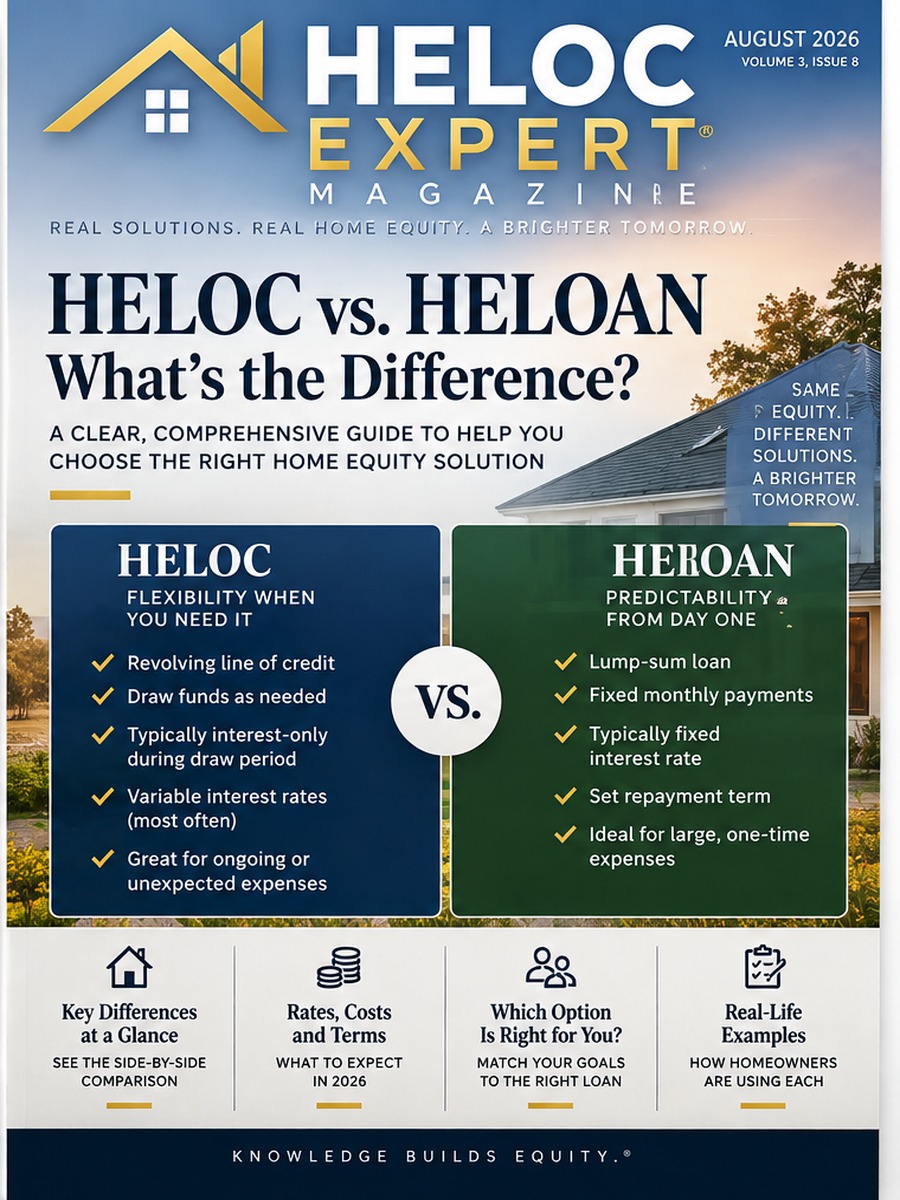
The August 2026 issue is intentionally narrow: HELOC versus HELOAN. Both products can allow homeowners to access equity without necessarily replacing the existing first mortgage, but they create different borrowing experiences. A HELOC is generally revolving and commonly variable-rate; a home equity loan is typically closed-end, lump-sum, and commonly fixed-rate.
Six features break the comparison into the dimensions that matter in real decisions: access to funds, rate structure, payment mechanics, transaction costs, and common homeowner scenarios. The goal is not to declare a winner. It is to make the structural differences clear enough that a borrower can recognize which tool better matches the intended use.
Both products can use home equity without replacing the first mortgage, but one is revolving credit and the other is usually a…
Read feature →HELOCs are commonly variable-rate while home equity loans are commonly fixed-rate, creating different types of payment uncertainty.
Read feature →A HELOC lets borrowers draw over time, while a HELOAN generally funds the full approved principal at closing.
Read feature →A lower HELOC payment during the draw period may reflect interest-only mechanics, while a HELOAN payment generally amortizes principal from the start.
Read feature →The quoted rate is only part of the HELOC-versus-HELOAN comparison; account fees, closing costs, early closure provisions, and holding period can change…
Read feature →Six scenarios show how timing, certainty, rate preference, and repayment style can point toward a HELOC or a home equity loan.
Read feature →