Using a HELOC as Business Liquidity: Flexibility, Discipline, and the Risk to Your Home
A HELOC can resemble a flexible source of working capital, but using home equity for a business creates a direct connection between…
Read feature → Request Options
A practical issue about using HELOC flexibility for business liquidity, weddings, home improvements, education, investor opportunities, and other planned needs—with a clear look at when borrowing against home equity may not fit.
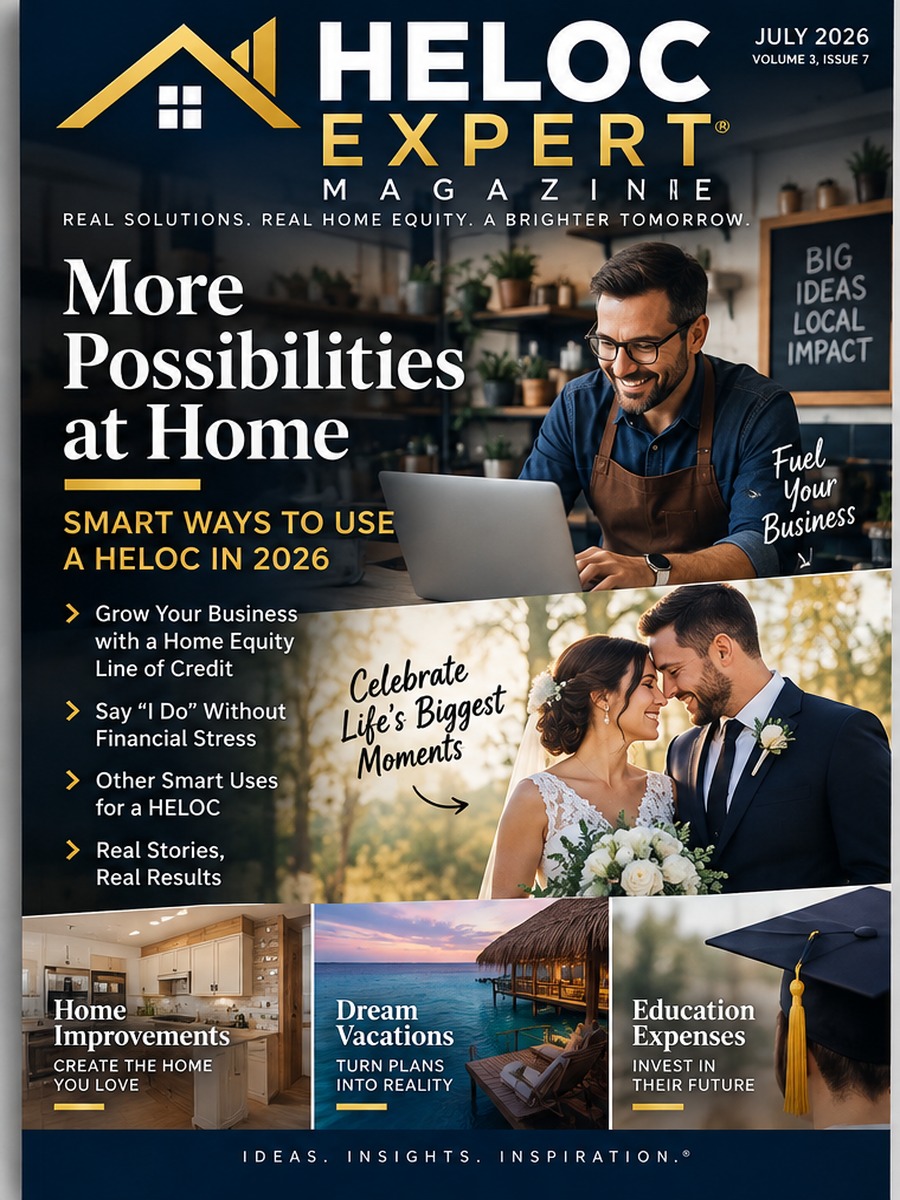
The July 2026 issue explores a question homeowners and investors ask after they understand how a HELOC works: what jobs can a revolving home-equity line reasonably perform? The answer depends less on the category of spending and more on whether the use is deliberate, the repayment source is visible, and the household or property can absorb the secured obligation.
Inside this issue, we examine business liquidity, wedding costs, home improvements, education expenses, investor opportunity reserves, and the warning signs that suggest a HELOC may be the wrong tool. The theme is flexibility with discipline—not borrowing simply because equity is available.
A HELOC can resemble a flexible source of working capital, but using home equity for a business creates a direct connection between…
Read feature →A HELOC can spread wedding expenses over time, but borrowing against a home for a one-day event deserves a strict budget and…
Read feature →Renovations often unfold in phases, making a revolving HELOC a natural structure to compare with a lump-sum home equity loan.
Read feature →A HELOC can provide flexible access for tuition and education costs, but student-loan protections and the use of a home as collateral…
Read feature →Investors may use home or property equity to create flexible opportunity capital, but borrowing capacity should not be confused with true cash…
Read feature →Flexible credit can be useful, but some spending patterns and financial conditions are warning signs that home-secured revolving debt may not fit.
Read feature →